Websites for private lenders
Private lender websites that bring in fundable deals
Websites for private mortgage lenders, MICs, bridge and hard-money lenders and business lenders that bring in fundable deals: a submission portal brokers actually use, a loan-scenario form that asks purpose and security before anything else, licence numbers where regulators expect them, and investor pages kept behind an eligibility check.
- Website from $150/month, yours after 12 payments
- SEO plans from $149/month
The short answer
What should a private lender website have?
A private lender website should state the loans you make, the property types and regions you lend on and how fast you decide, then take a deal through a short scenario form or a broker submission portal. It should show your licence or NMLS number where required, avoid quoting rates casually, and keep any investor offering behind an eligibility step.
- Price
- $1,500 upfront, or $150/month × 12
- Ownership
- Yours after 12 payments
- Hosting and care
- $29 or $49/month
- Build time
- About 4 weeks for a local site
Our designs
Our website and app designs for private lenders
Ready-to-launch concept designs for fictional businesses: pick one and make it yours. 6 websites, 1 app and 1 software design, each opening on a desktop and a phone, with your brand, content and photos going in. All apps and software
8 of 8 examples shown
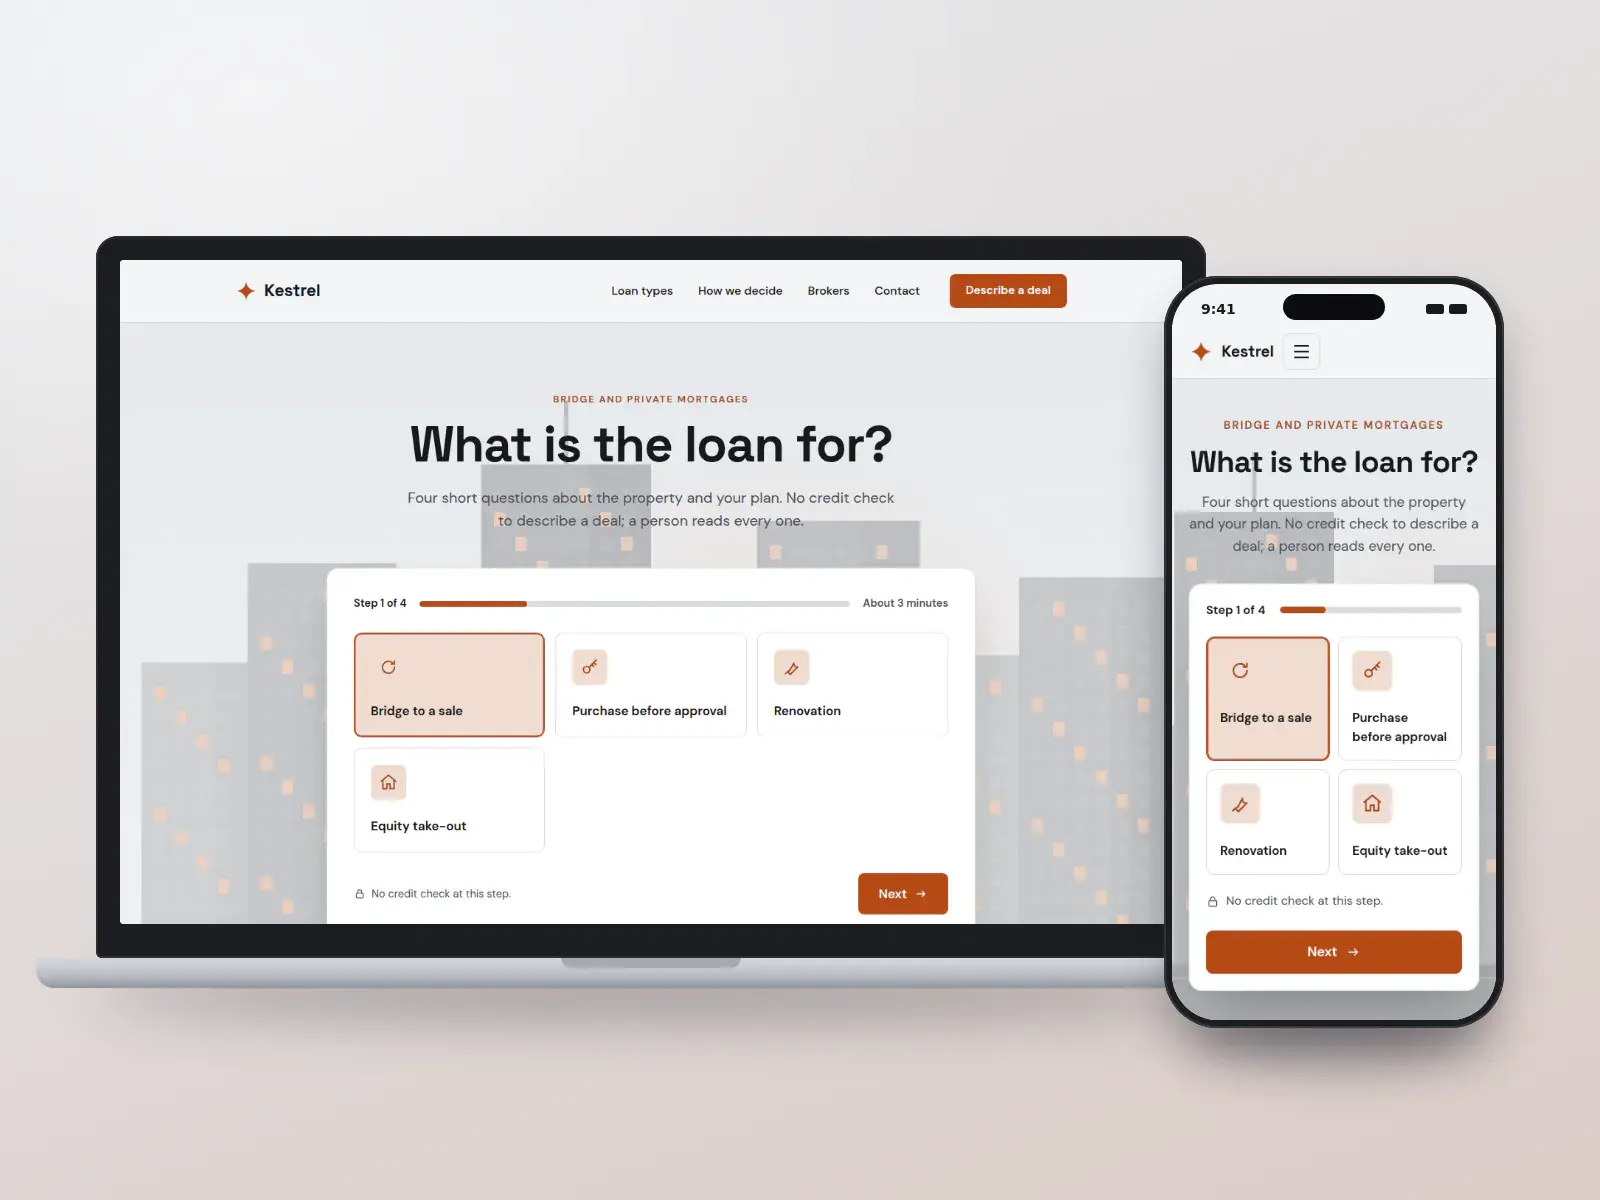
Concept website
Kestrel Bridge Capital
Bridge and hard-money mortgage lenders
Concept design. The business is fictional.
- Tool-first
- Bold
Local website: yours after 12 payments, or $1,500 upfront
Concept website
Quayline Lending
Lenders funded mainly through mortgage brokers
Concept design. The business is fictional.
- Dark
- Tool-first
Growth website: yours after 12 payments, or $4,000 upfront
Concept website
Granite Mile Mortgage
Established private lenders with a track record
Concept design. The business is fictional.
- Corporate
- Bold
Growth website: yours after 12 payments, or $4,000 upfront
Concept website
Larkspur Mortgage Investment Corporation
Mortgage investment funds raising capital
Concept design. The business is fictional.
- Dark
- Luxury
Growth website: yours after 12 payments, or $4,000 upfront
Concept website
Saltbox Business Credit
Business-purpose and equipment lenders
Concept design. The business is fictional.
- Corporate
- Friendly
Local website: yours after 12 payments, or $1,500 upfront
Concept website
Fenwick Lane Capital
Commercial and investor-property lenders
Concept design. The business is fictional.
- Editorial
- Luxury
Local website: yours after 12 payments, or $1,500 upfront
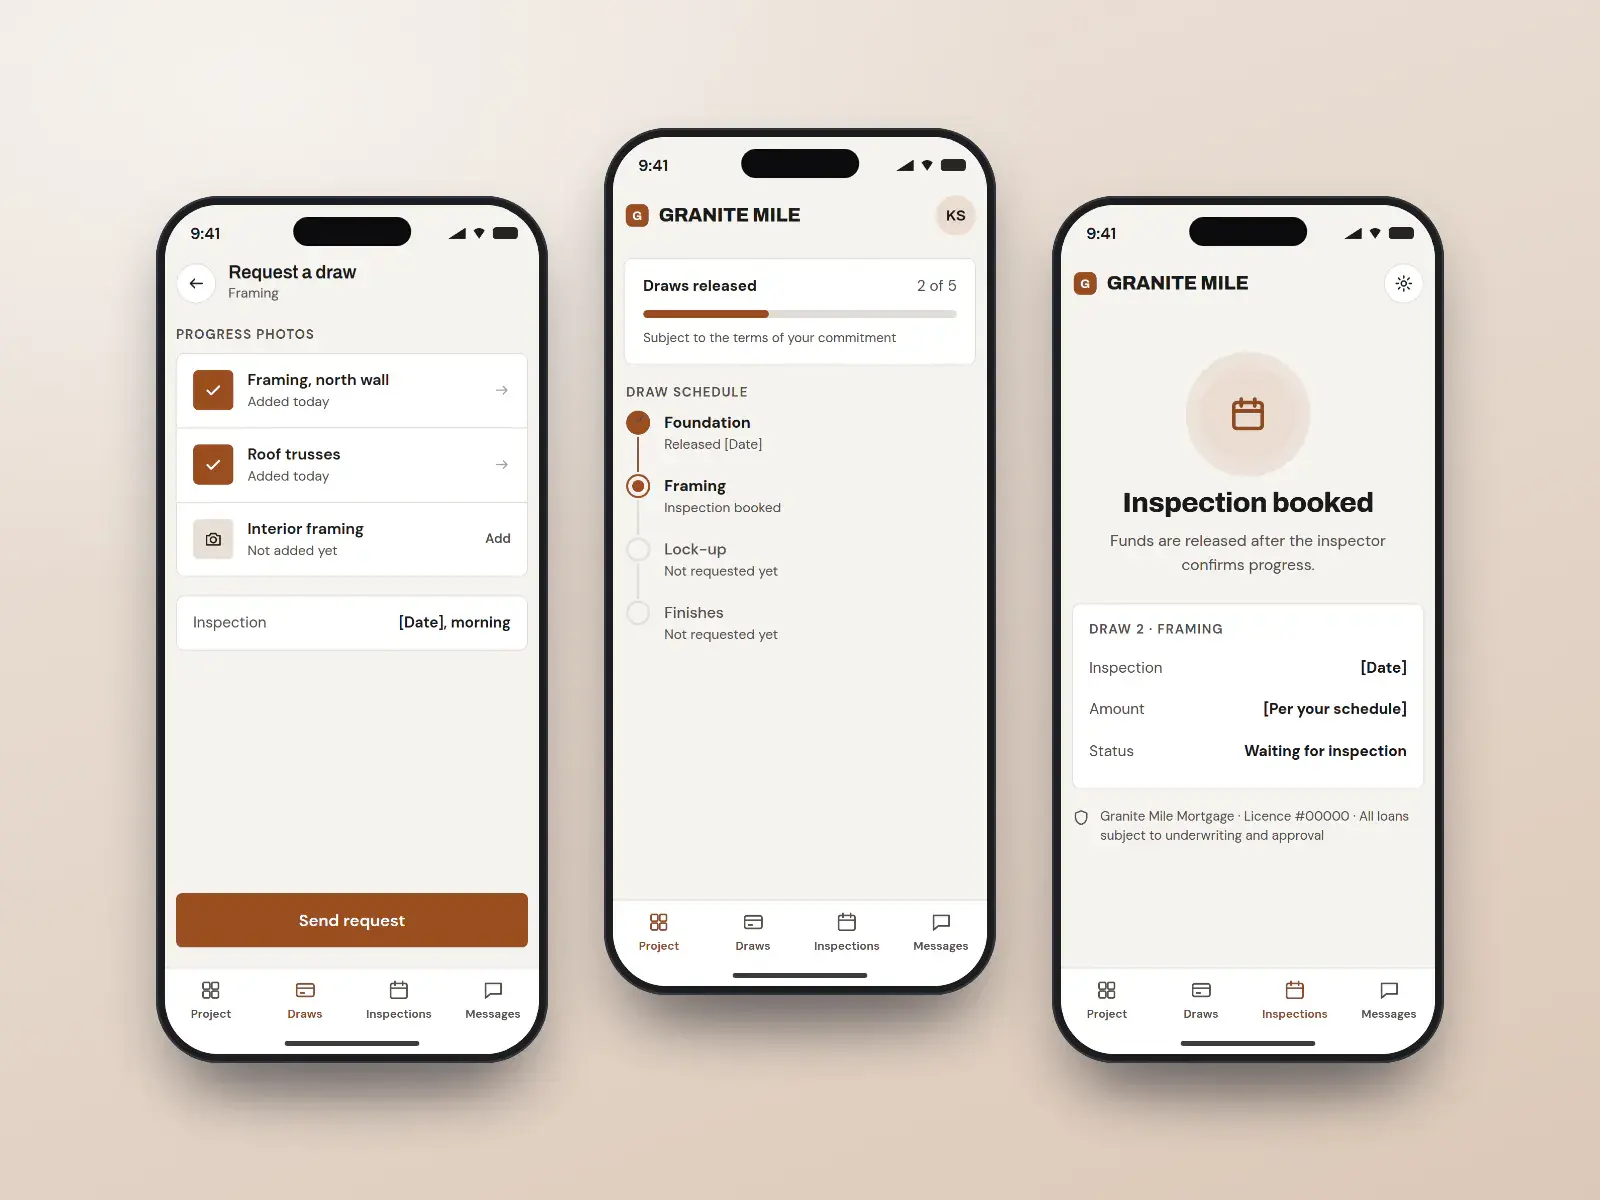
Concept app
Granite Mile draw app
Construction borrowers requesting draws
Concept design. The business is fictional.
- Corporate
- Tool-first
Quoted per project after a call
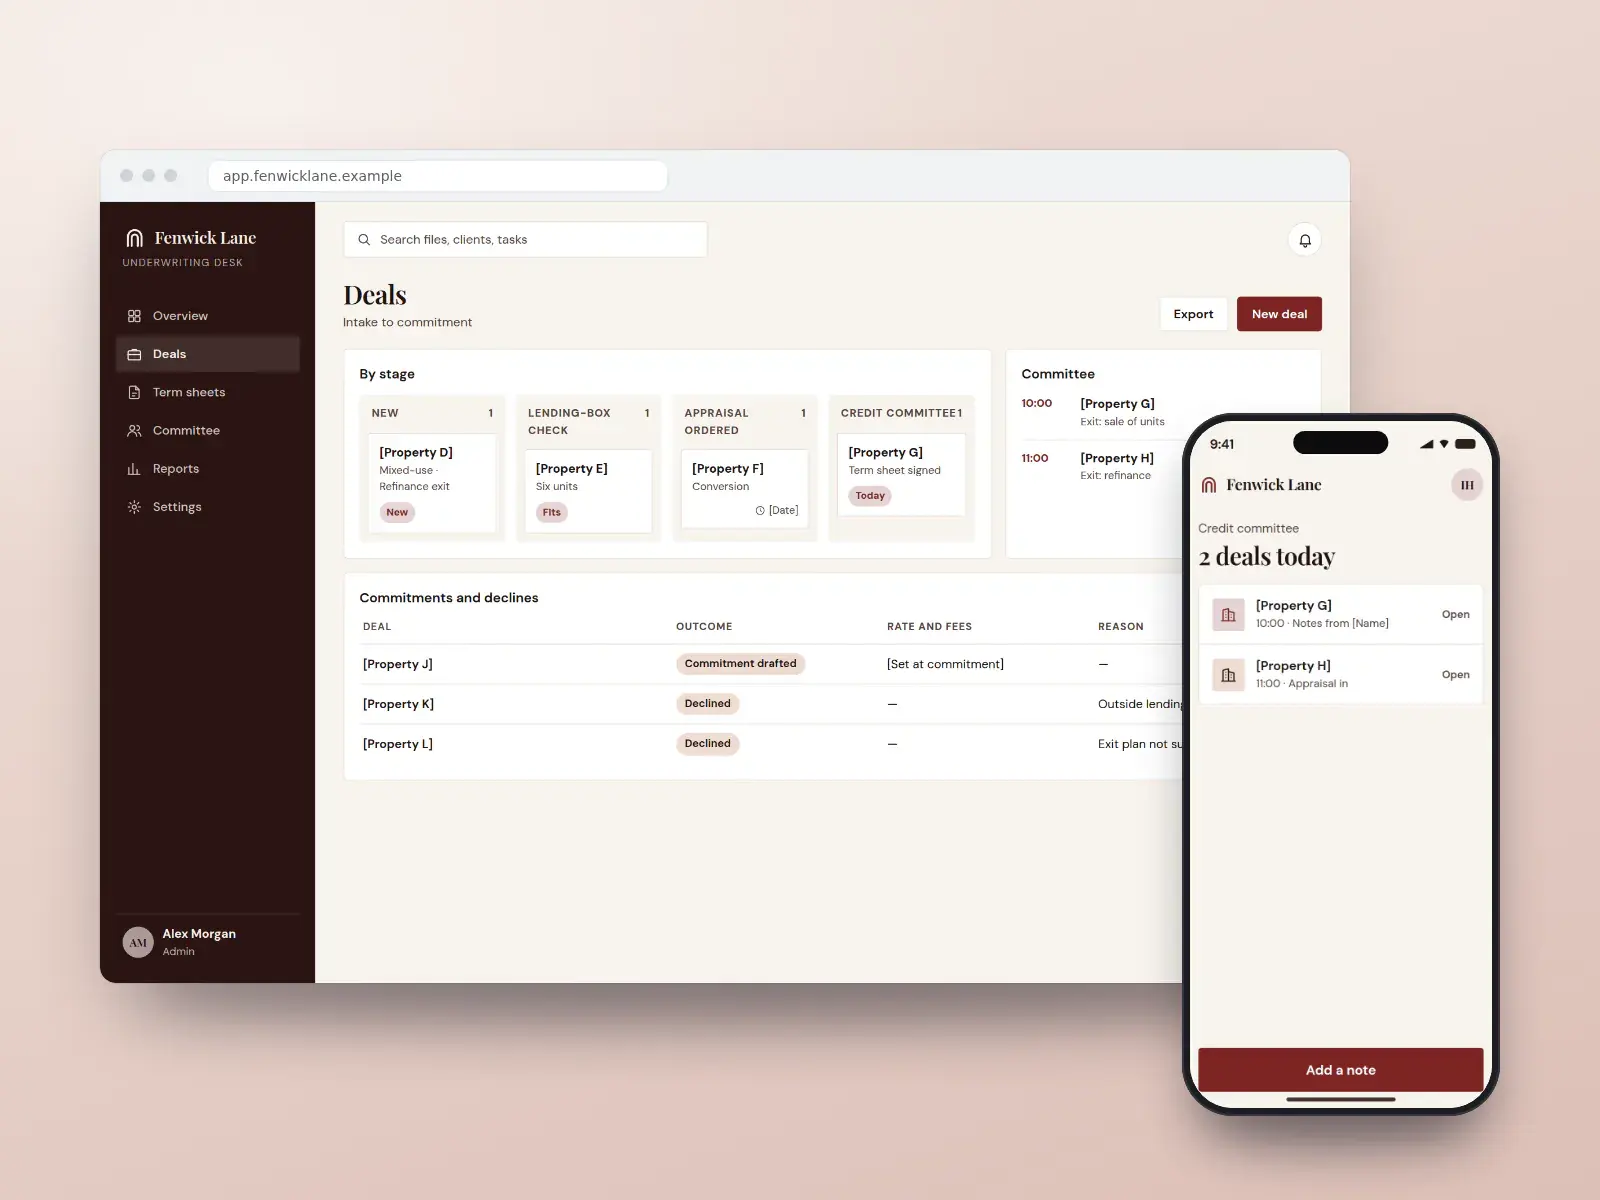
Concept software
Fenwick Lane underwriting desk
Lenders running deal intake and underwriting
Concept design. The business is fictional.
- Data-led
- Editorial
Quoted per project after a call
Pay monthly, own it
High-converting websites from $150/month
Pick a design, add your brand, content and photos, and launch. Yours after 12 payments, with SEO built in from day one.
- Local website
- $150/monthUp to 25 pages · yours after 12 payments, or $1,500 upfront
- Growth website
- $400/monthUp to 100 pages · yours after 12 payments, or $4,000 upfront
Built in
What every private lender website includes
A loan-scenario form that asks about the security
Purpose, property type, position, amount range and exit come first. That is what a private underwriter decides on, and it filters out deals you would never fund.
A broker submission portal
Approved brokers submit files, upload appraisals and clear conditions in one encrypted place, and see a named underwriter on every deal instead of chasing by phone.
Licence and NMLS numbers in the right places
Your brokerage, administrator or state lending licence numbers in the footer and on the application, set once and repeated wherever a regulator expects them.
Investor pages behind an eligibility step
Public pages explain what the fund or MIC is and its risks; the offering memorandum and financials open only after the visitor confirms they qualify under an exemption.
Funded deals as proof, without terms
A ledger of closed loans by property type, purpose and region, with amounts you verify and a line saying past deals are not an offer of credit.
Consumer and business paths kept apart
Business-purpose loans and consumer mortgages get separate pages and forms, so the advertising rules that apply to one do not leak onto the other unnoticed.
How clients search
The searches and pages a private lender website needs
Two kinds of people look for a private lender, and they search differently. A borrower the bank turned down, or one racing a closing date, searches on a phone in plain, urgent words: “private mortgage lender”, “bridge loan to buy before selling”. Mortgage brokers and property investors search by deal type and region, then judge the lending box, the turnaround and who underwrites. Both look up the licence and any complaints before they send a single document.
- “private mortgage lender near me”
- “bridge loan to buy before selling”
- “hard money lender for fix and flip”
- “second mortgage from a private lender”
- “private construction loan”
- “business purpose loan secured by real estate”
- “how do private mortgages work”
- “mortgage investment corporation explained”
- 01
Loan programs by purpose
One page per loan you actually fund, such as bridge, construction, second mortgage, equity take-out or commercial, each naming the property types, positions and regions you lend on. These match how borrowers and brokers search, and none of them needs a rate to be useful.
- 02
The lending box, for brokers
Regions, property types, positions and the limits you work within, described in words, plus how a brokerage becomes approved. A broker decides in a minute whether a file fits, and a clear page saves both sides a wasted submission.
- 03
How private mortgages work
An explainer on fees, terms, renewals, independent legal advice and the exit plan, for a borrower who has never used a private lender. It answers what assistants get asked about private lending and sets honest expectations before the first call.
- 04
Scenario or term-sheet request
A short form asking purpose, property, amount range and exit, with a promise of a reply from a person. It converts search and referral traffic alike, and gathers what underwriting needs without a credit check at the first step.
- 05
Licences and complaints
Licence numbers, the NMLS ID where it applies, a link to the regulator’s public lookup and how to raise a complaint. Brokers and borrowers check this before sending documents, and several regulators expect licence details in advertising anyway.
- 06
Investor information, gated
For a lender that raises money through a MIC or fund, a public page on the structure and its risks, with offering documents behind an eligibility step securities counsel approves. It stops the borrower site becoming an accidental solicitation.
SEO, AEO and GEO
How private lenders get found in Google and in AI answers
A business profile under the licensed name
Categories such as Mortgage lender or Loan agency, chosen to match the licence, with the authorized name exactly as registered. A lender that works only through brokers still benefits: a search for its name then shows an address, hours and a phone someone answers.
Pages by region and deal type
Brokers and investors search by place and purpose, for example a construction lender in a named city. A page for each region you lend in, listing the loan and property types funded there, matches those searches far better than one generic homepage can.
Guides assistants can quote safely
People ask AI assistants how bridge loans, second mortgages and MICs work and what they cost. Guides that open with a short answer, carry a named author with lending experience and a review date, and state no rate an assistant could repeat out of context are the ones worth citing.
Markup without loan terms
Organization or FinancialService markup with licence identifiers and FAQ answers that also appear on the page. No rates, fees or yields in structured data, where they could surface in results without the disclosures that must travel with them.
Compliance
The rules for private lenders, handled in the design
Private lenders answer to mortgage licensing regulators, consumer-credit rules and, once they raise investor money, securities law. These are the rules that shape a lender’s licence lines, loan advertising and investor pages, and what each design does about them.
Sources gathered October 6, 2026. This is how our designs handle these rules, not legal advice: rules change and differ by province and state, so your lending counsel or compliance officer has the final word, and you approve every page before it goes live.
- Ontario · FSRA
Lending and administering mortgages need a licence
Under Ontario’s Mortgage Brokerages, Lenders and Administrators Act, 2006, carrying on a mortgage lending business generally needs a brokerage licence, and administering mortgages for others needs an administrator licence, with exemptions such as financial institutions. Ontario designs carry the right licence type and number in the footer.
FSRA — About mortgage brokerage and mortgage administrator licences
- Ontario · FSRA
Licensed name and number in every advert
FSRA says every public relations material, a website included, must clearly and prominently show the brokerage’s or administrator’s authorized name and licence number, and the regulations govern how an interest rate or cost of borrowing (APR) may be advertised. The designs show the authorized name and number and quote no cost of borrowing.
FSRA — Mortgage industry public relations and advertising requirements
- Canada · securities law
MIC shares and syndicated mortgages are securities
Investor money is raised under prospectus exemptions such as those in NI 45-106, and since July 2021 the Ontario Securities Commission oversees non-qualified syndicated mortgages sold to investors who are not permitted clients. Investor pages explain risk publicly and keep offering documents behind an eligibility check.
- US · Regulation Z §1026.24
Trigger terms in consumer credit ads
For consumer credit, stating a payment amount, number of payments, down payment or finance charge triggers further disclosures, and a rate must be stated as an APR. Business-purpose credit is exempt under §1026.3(a). The designs quote no terms at all, and consumer pages are reviewed before any term is added.
- US · Regulation B §1002.4(b)
Nothing that discourages applicants
Regulation B bars statements, in advertising or otherwise, that discourage applicants on a prohibited basis. The CFPB’s April 2026 final rule, effective 21 July 2026, narrowed it to statements a creditor knows or should know would make a reasonable person expect denial or worse terms on that basis. Copy describes loans and security, never the kind of person who should apply.
- US · SAFE Act and states
NMLS IDs and state lending licences
Residential mortgage lenders licensed through NMLS must provide their unique identifier, and many states require it in advertising and on websites, alongside state licence and usury rules. US designs carry the NMLS ID and state licence placeholders where a lender is licensed.
- US · SEC Rule 506(c)
General solicitation only to verified accredited investors
A US fund that advertises publicly under Rule 506(c) must take reasonable steps to verify every purchaser is accredited (a March 2025 staff no-action letter accepts high minimum investments plus written representations); a 506(b) offering cannot generally solicit at all. US investor pages stay closed until eligibility is confirmed, as fund counsel directs.
- Canada · Criminal Code s.347
The criminal interest rate is 35% APR
Since 1 January 2025 the criminal rate in Canada is 35% APR, and lender fees and most other charges for the credit count toward it. Regulations exempt business-purpose loans above ten thousand dollars to borrowers that are not individuals, capped at 48% APR up to half a million dollars and uncapped above. The designs quote no rates or fees.
Everything for private lenders
Websites, apps, branding and SEO for private lenders
Websites
Private lenders websites built on the designs above, fast and set up for search.
From $150/month
Apps
A private lender’s busiest users are mortgage brokers and borrowers mid-deal. An app pays off when it removes the “any update on my file?” call.
Quoted per project
Apps for private lendersBranding
Private lending is a relationship business with a reputation problem. A brand has to look solid enough for brokers and investors and plain-spoken enough for a borrower the bank turned down.
Quoted per project
Branding for private lendersSEO and leads
Ongoing SEO that checks your site every week and fixes what is safe to fix, for more fundable deals and broker submissions.
From $149/month
SEO plans and prices
Pricing
What a private lender website costs
The price of a private lender website is the same as any website we build: pay upfront and save, or spread it over 12 months.
Local website
$150/month × 12
or $1,500 upfront. Yours after the 12th payment.
- Up to 25 pages
- Any design on this page
- Technical SEO at launch
- Hosting and care $29/month
Growth website
$400/month × 12
or $4,000 upfront. Yours after the 12th payment.
- Up to about 100 pages
- Teams, offices and more integrations
- Planned with an advisor
- Hosting and care $49/month
SEO plans
$149/month
Local $149 · Growth $399
- Checks your site every week and fixes what is safe to fix
- New pages every month
- 7-day trial
Prices in US dollars. How payments, hosting and ownership work.
How it works
How your private lender website goes live
- 01
Pick a design
Choose one, or ask for something new. Tell us the loans you make, where you lend and whether brokers or borrowers come first.
- 02
Send your details
Logo, licence and NMLS numbers, your lending box, funded deals you can verify and any investor documents.
- 03
Review before launch
Your counsel and compliance check every disclosure, investor gate and consumer page before launch.
- 04
Launch and grow
We go live, connect the portal and build loan-type and region pages that bring in deals.
Pick my design
See your website before you pay for it
Choose a design and tell us about your business. An advisor emails you to plan a preview with your name, your colours and your details, and the price options. Nothing is charged until you decide.
- 1An advisor replies by email
- 2We plan your preview and scope
- 3You decide, with every price in writing
Questions
Private lenders: common questions
- How much does a private lender website cost?
- A private lender website of up to 25 pages is $1,500 paid upfront, or $150 a month for 12 months, and it is yours after the 12th payment. A larger site of up to about 100 pages is $4,000, or $400 a month. Hosting and care is $29 or $49 a month. Prices are in US dollars.
- Should a private lender publish rates on its website?
- Usually not. Private loans are priced on security, position and exit, so a published rate is often wrong for the next deal. On consumer loans a stated rate or payment brings in disclosure rules such as Regulation Z’s APR and trigger terms in the US, or Ontario’s cost-of-borrowing rules. The designs ask for the scenario and reply with terms in writing.
- Can a mortgage investment corporation advertise to investors on its website?
- Only within the prospectus exemption it relies on, and the rules differ by province and between Canada and the US. The designs keep investor pages educational and risk-first in public, and open the offering memorandum and financial statements only after the visitor confirms they qualify, with your securities counsel setting the wording.
- What licence details does a private lender’s website need to show?
- It depends where you lend. In Ontario, FSRA expects a brokerage or administrator’s authorized name and licence number in advertising. US residential mortgage lenders licensed through NMLS show their NMLS ID where states require it. Each design has a footer and application line for these, set once and filled with your real numbers.
- Can mortgage brokers submit deals through a private lender’s website?
- Yes. The broker portal lets approved brokerages submit a deal, upload appraisals and statements, and see outstanding conditions and the named underwriter on each file. Borrower information stays inside the encrypted portal rather than in email, and brokers sign in with a one-time code.
- Does a private lender need a website if most deals come from brokers?
- Yes. Brokers look at a lender’s site before sending a client’s file: the lending box, who underwrites, the licence and how quickly decisions come back. Borrowers do the same once a broker names you. A clear site with a submission portal cuts wasted files, and loan-type pages bring direct scenarios from investors and borrowers who search by purpose.
- Will my private lender website rank on Google?
- It launches with the technical SEO done: fast pages, clean structure, structured data, local pages and redirects from your old site. To keep climbing, a BOOSTD SEO plan from $149 a month runs 262 checks on your site every week, fixes what is safe to fix and gets the rest ready for your OK.No one can promise a position on Google, and we never do. Google warns businesses about anyone who does.
- Can I get one of these private lending website designs?
- Yes. Each is a complete, ready-to-launch website design BOOSTD made for private lenders. Pick one and we make it yours, with your name, colours, photos, content and the licence or compliance details your industry expects, from $150 a month and yours after 12 payments.Approved client sites are shown with a “Client work” tag, and only with the client’s written permission.
Guides for private lenders
Reading for private lenders before you build
- Planned guideWhat a private lender website can say without quoting ratesPlanned: written with a named author and published once reviewed
- Planned guideBuilding a broker submission portal mortgage brokers will usePlanned: written with a named author and published once reviewed
- TrackingConversion tracking for calls and forms in GA4 and Google Ads
More on private lender website
- Websites for property managers
- Marketing for business lenders SEO and lead generation for lenders.
- Websites for mortgage brokers
- Websites for real estate lawyers
- Tracking calls and form submissions
- A quote for a private lender with many offices More locations than a plan covers? Tell us about the network.
Free, about a minute, nothing changes on your site
Start with a free checkup of your current site
See what holds your current website back across every point, free, before you choose a design.
- Free, no cardNo sign-up to see your preview.
- Read-onlyNothing changes on your website.
- 90-day guaranteeIf you join: a better score, or your next month free.